News · FX & macro · openbook · Fri, Nov 6, 2026 8:49 AM
Risk-Off Before Payrolls: Yen Gains as AI Stocks Fall
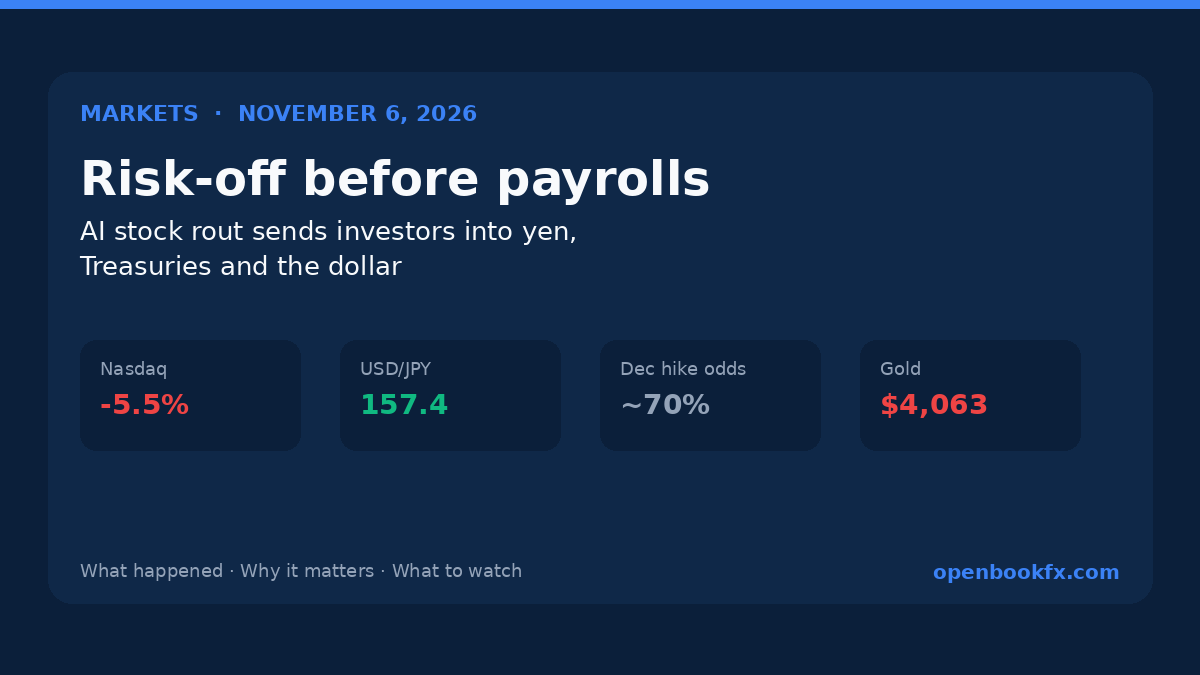
Image from the source feed · openbook
US equities sold off hard on AI fears. See how the yen, dollar, Treasuries and gold reacted, and why Friday’s payrolls report matters for Fed hike odds.
Global markets opened Friday, November 6, in a clear risk-off mood. A sharp selloff in US equities on Thursday, led by artificial-intelligence and semiconductor stocks, pushed investors toward haven assets such as the Japanese yen, the Swiss franc and US Treasuries. Attention now turns to the US nonfarm payrolls report due later Friday, which will help shape expectations for the Federal Reserve's next move.
What happened
Thursday's session was the steepest drop in US stocks since the tariff-driven "Liberation Day" rout in April 2025. Closing reports showed:
- The Nasdaq Composite fell 5.52% to 24,315, its largest decline in about 19 months.
- The S&P 500 lost about 4.4% to 7,353, with all 11 sectors lower and roughly $3 trillion of index value erased.
- The Dow fell 3.44% to 51,523; the Nasdaq 100 dropped 6.4% and the Philadelphia Semiconductor Index about 12.3%.
A Democratic sweep of Congress in the midterms raised fears of tighter scrutiny of the AI industry, especially around data-center construction. That concern spilled into Asia on Friday. Bitcoin fell about 6% to around $75,700 as risk appetite drained from speculative assets more broadly.
How FX and bonds reacted
When equities sell off this hard, money often rotates into assets seen as safer:
- The yen strengthened to a one-week high near 157.40 per dollar before giving back some of the move. OCBC analysts noted that falling US yields can blunt the dollar's haven appeal, leaving the yen as a preferred hedge against US-centric volatility.
- The Swiss franc firmed about 0.2% against the dollar, while the dollar index held near 101.55–101.76.
- EUR/USD hovered around 1.12; sterling was near $1.34–$1.35 after the Bank of England raised rates as expected.
In bonds, the 10-year US Treasury yield fell toward about 4.84%, near its lowest since September 10. The two-year yield dropped roughly 10 basis points overnight to around 4.47%.
Why this matters for Fed pricing
Lower front-end yields also reflected a repricing of Fed expectations. Fed funds futures scaled back the probability of a 25-basis-point December hike to around 68–70%, down from more than 80% on Wednesday, according to traders and CME FedWatch readings reported by major wires.
Friday's payrolls report is one of the last big labour prints before the December meeting. A strong number could push hike odds and the dollar back up; a soft print could keep haven currencies and bonds bid. Leading indicators leaned firm: weekly initial jobless claims fell by 6,000 to 189,000, matching a 57-year low and coming in below the 196,000 Reuters consensus.
Gold, oil and the inflation cross-current
Spot gold eased about 0.6% to around $4,063 an ounce early Friday after rising to $4,088.39 on Thursday, but was still up roughly 4% on the week. Haven demand supported bullion, while a rebound in oil raised inflation worries. Brent had jumped about 4.7% on Thursday to around $99 a barrel. Higher energy costs can keep the Fed cautious — one reason Goldman Sachs cut its end-2026 gold forecast to $4,150 from $4,650.
What to watch next
- US nonfarm payrolls (Friday, 13:30 GMT). Reuters consensus is for about 65,000 jobs in October after September's 29,000. Unemployment is expected near 4.2%, with average hourly earnings up about 0.3% month on month (around 2.9% year on year).
- The mix, not just the headline. Revisions, wages and the jobless rate often move FX and yields as much as payrolls itself.
- December Fed hike odds. Watch whether the roughly 70% probability holds, rises toward 80%, or falls further.
- USD/JPY and EUR/USD. The yen's haven bid and the euro's weekly rebound will be tested if a hot jobs report revives the dollar.
- Whether the AI selloff broadens. Defensives held up better than tech on Thursday; further semiconductor weakness would keep risk fragile into next week.
Friday is a classic lesson in how equity risk, bond yields and currencies move together. The same news that hits the Nasdaq hardest can strengthen the yen, flatten Fed hike odds and leave gold torn between haven demand and rate fears.
Sources: CNBC, Reuters, FXStreet, ATFX, MarketScreener, CME FedWatch. Prices and probabilities as reported in early Friday, November 6, 2026 Asian/European hours. This article is for educational purposes only and is not investment advice.
Read our USD/JPY guide: what moves it, the key data to watch and when it trades.
This briefing was summarized with automated tools from public reporting by openbook and is general market information, not investment advice. Editorial policy & corrections